
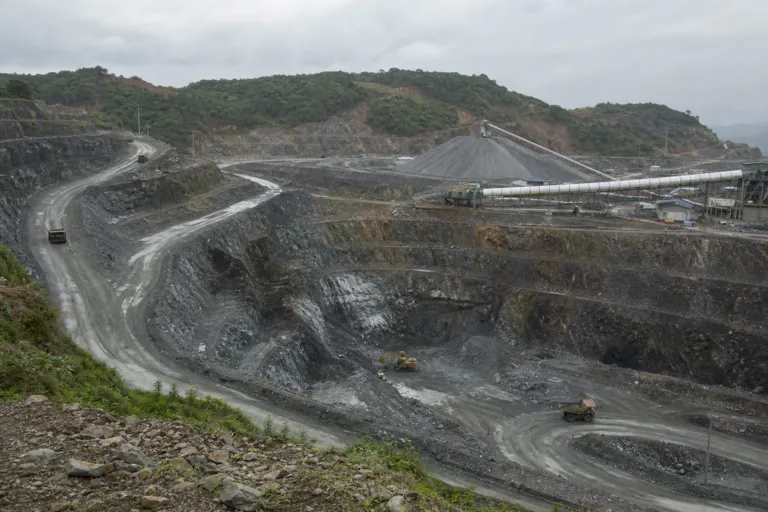
The Philippines is described as the fifth most mineralised country in the world, with an estimated USD1 trillion in untapped reserves spanning copper, gold, nickel, zinc, and silver. Recent MGB statistics cited in 2026 guidance indicate 60 operating metallic mines and 61 operating non-metallic mines, employing around 291,672 workers. In 2024, total exports of minerals amounted to almost USD7.38 billion, while the MGB placed the mining sector’s gross production value at PHP316.29 billion. Within that mix, gold became the largest contributor, replacing nickel and related products, with an estimated production value of PHP126.36 billion from 28,870 kilograms produced in 2024.
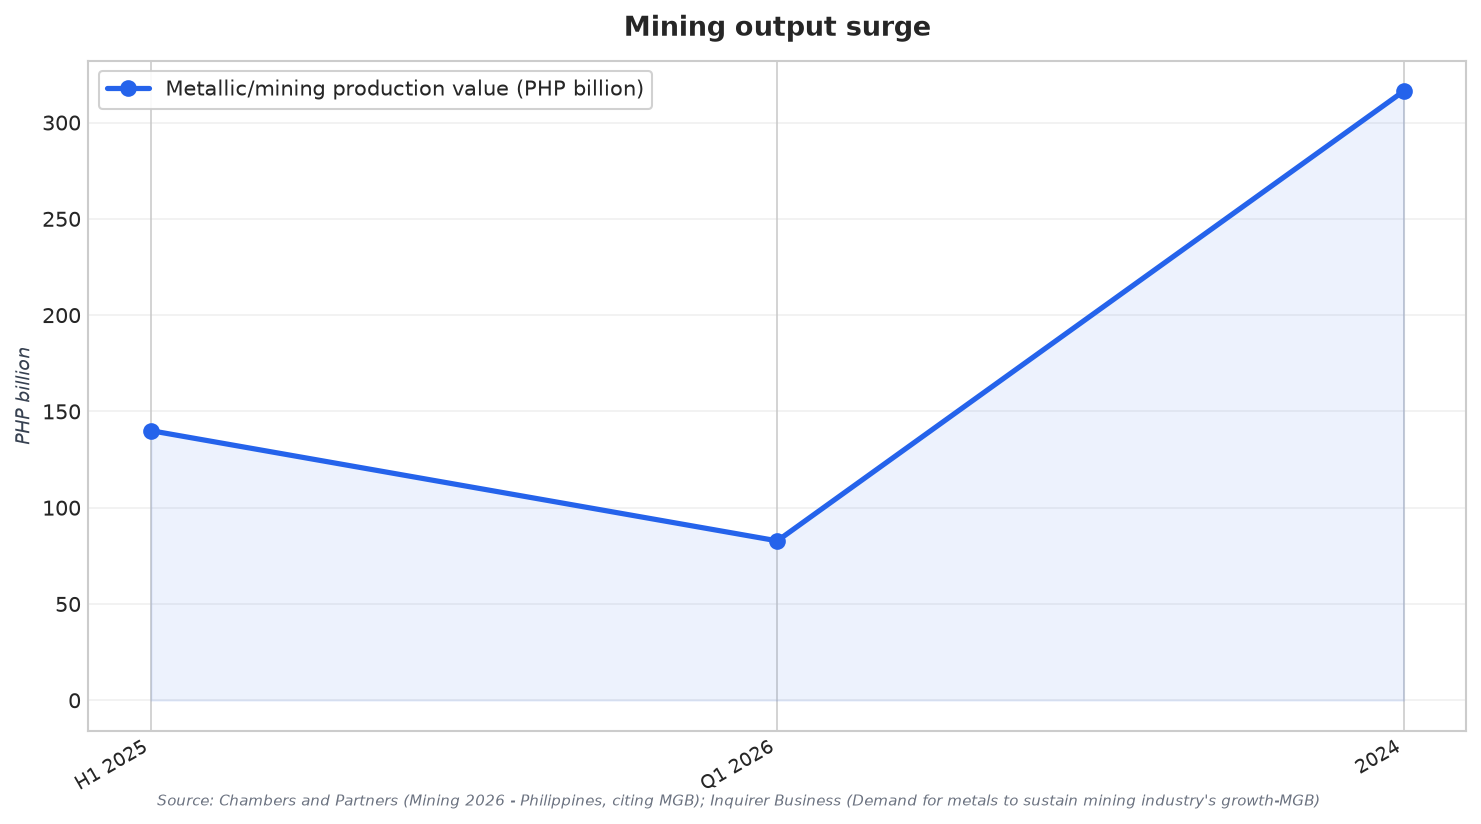
Momentum carried into the next reporting periods. For the first semester of 2025, gross metallic production reached PHP140 billion, representing a 21.98% increase from the same period a year earlier, attributed in the same source to higher global gold prices, increased output from operating mines, and favourable market and regulatory conditions. In the first quarter of 2026, MGB data reported metal production up 28.6% to P82.78 billion, with the increase mainly driven by higher metal prices and improved output in selected commodities. This sequence matters for a Philippines copper-gold mining investment 2026 thesis because it frames the sector as one where price cycles and operational output can translate quickly into value metrics.
Copper’s Export Model Meets a Domestic Processing Gap
The country’s copper market structure is split between upstream concentrate exports and downstream reliance on imported refined copper. A 2026 copper market report describes the Philippines refined copper market as a net importer, with refined copper entering almost entirely via seaborne trade, while domestic copper mining produces primarily copper concentrate exported for smelting abroad rather than refined locally. The same report estimates refined copper consumption in the range of 80,000 to 120,000 tonnes annually and says growth in market volume averaged 2-4% annually over the past five years, with a projected 2026-2035 CAGR of 3-5%. In value terms, it notes LME copper prices ranging between approximately USD 8,000 and USD 11,000 per tonne in recent years, shaping volatility for buyers and suppliers.
On the mining side, an ores and concentrates report estimates Philippine copper ore production at 250,000-400,000 tonnes of contained copper annually. It also places copper concentrate export volumes typically at 400,000-700,000 dry metric tonnes per year, with over 80% destined for China, Japan, and South Korea. It characterizes ore grades from Philippine operations as typically 0.3% to 0.6% copper, with concentrate grades of 25-30% copper, and notes benchmark treatment and refining charges ranging from USD 20-80 per dry metric tonne. Separately, MGB data reported that in the first quarter of 2026, the quantity and value of copper concentrate dropped by 19.4% and 7.4%, ending at 47,920 DMT and P6.4 billion, underscoring near-term variability even within a structurally export-oriented model.
Investors also have to price in governance, permitting, and community consent dynamics because they directly affect project timelines and expansion. The mining industry is governed primarily by the Philippine Constitution and the Philippine Mining Act (Republic Act No 7942) and its IRR, with DENR and the MGB issuing administrative orders and related instruments that form part of the regulatory framework. Under the Constitution, the state owns all natural resources and has full control and supervision over exploration, development, and utilisation, while the President may enter into agreements with foreign-owned corporations involving technical or financial assistance for large-scale projects. Community access agreements can be pivotal: a 2026 corporate update noted access agreements signed in June 2026 with Balatoc (Kalinga) Tribe, Inc. and the Philippine Mining Development Corporation for a 440-hectare copper-gold porphyry area, while also stating there was no public confirmation of drilling as of late September 2026.
What makes gold central to the Philippines mining revival?
How big is the Philippines’ refined copper demand, and why does it matter?
Where does Philippine copper concentrate typically go?
What do 2026 MGB data say about metal output momentum?
What should investors watch in a Philippines copper-gold mining investment case for 2026?