Singapore’s REIT sector enters 2026 with cautious optimism after two years of interest rate headwinds. The Kopi Notes frames 2026 as an inflection point as Singapore 3-month SORA eases toward 3.0% from a 2024 peak of about 3.8%, slowing the pace of distribution per unit erosion from higher interest expenses. As at Q1 2026, the iEdge S-REIT Index is described as having recovered modestly, with industrial, logistics and data centre sub-sectors leading the rebound. That matters for investors because the “bright spot” is not just performance-driven. It is also linked to a cost-of-debt backdrop that is gradually becoming less punitive, especially for REITs with fixed-rate debt and staggered refinancing profiles.
Operationally, Singapore’s industrial market is holding up in a way that supports both rents and sentiment. JLL cites JTC industrial property statistics showing the All Industrial Rental Index rose 0.4% quarter-on-quarter in 1Q 2026, while the All Industrial Price Index increased by 1.2% quarter-on-quarter. In the same JLL update, the firm estimates the All Industrial Rental Index for full-year 2026 may see a moderate upside of 1–2%, and the All Industrial Price Index some 2–3%. The reasoning is not a single-factor story. JLL points to continued AI-led investment and resilient electronics demand, and notes that higher-specification industrial and logistics assets should see support even as rents follow a more modest path alongside prices.
What the 2026 Industrial REIT Scorecard Says About “Tight at Home”
PropertyAtlas’s scorecard pulls the narrative into listed portfolios and highlights why domestic exposure is a key differentiator. It reports that eight SGX-listed REITs own industrial or logistics property in Singapore, ranging in scale from CapitaLand Ascendas at S$12.5 billion to Alpha Integrated at S$0.5 billion. The strongest rental reversions are linked to Singapore concentration: Alpha Integrated records +12.0% (a fully Singapore portfolio), ESR-REIT posts +9.2% (over 80% Singapore by rental income), and CapitaLand Ascendas logs +12.8% on its Singapore business-space and life-sciences leases specifically. Yet diversification can dilute the headline number. Mapletree Logistics shows +3.3% blended reversion, with the article attributing the gap to geographic drag from China where reversions are still negative even as they narrow.
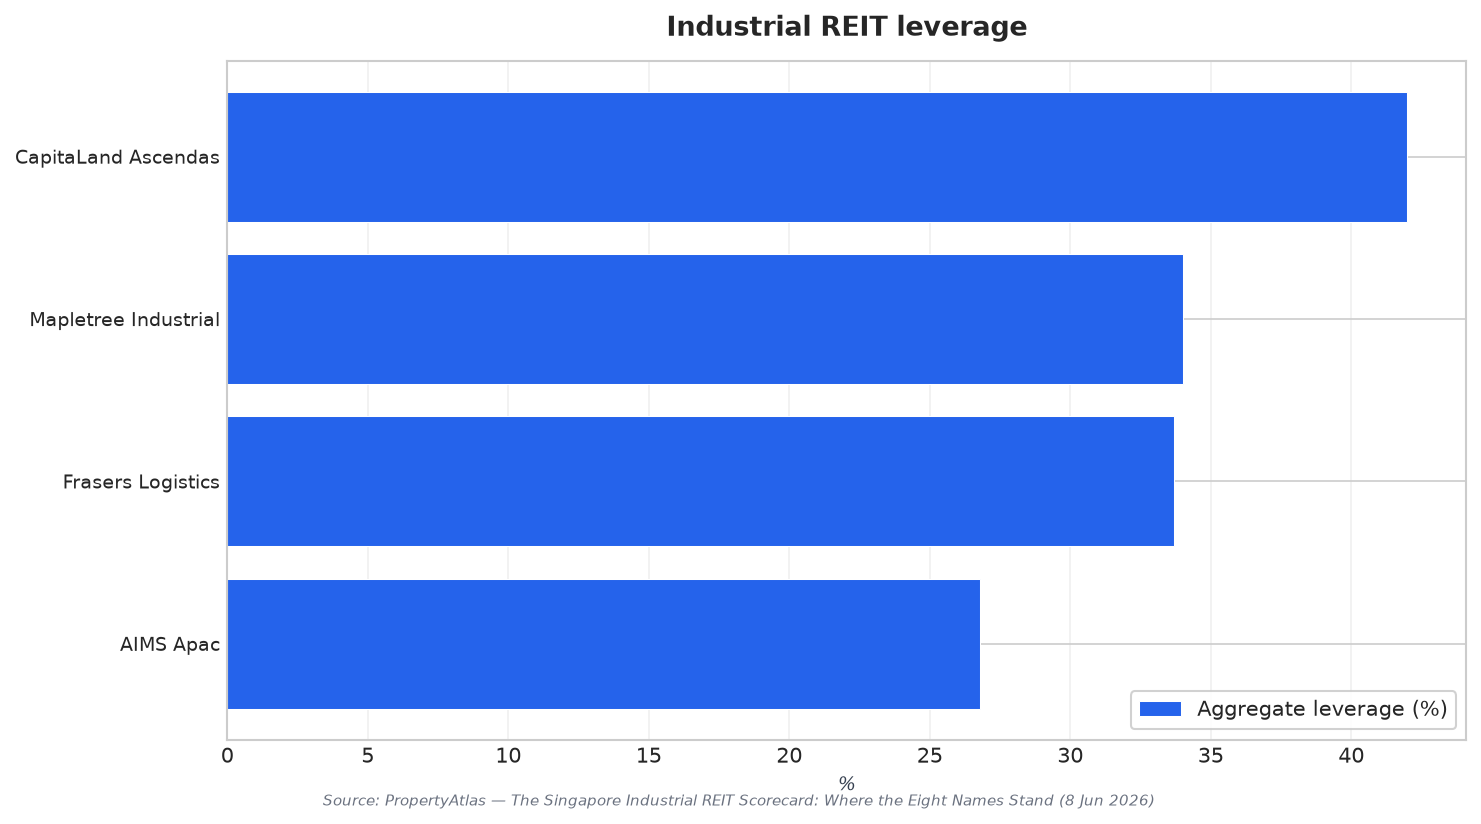
Income is the other half of the “sheds and yields” story, and the sources underline how industrial, logistics, and data centres have been priced and occupied. The Kopi Notes states that average distribution yields in the industrial, logistics and data centre sub-sector sit around 5.5–6.5% as at Q1 2026, alongside data centre occupancy described as 95%+ and positive rental reversion. PropertyAtlas adds balance-sheet context: aggregate leverage spans 26.8% to 42.0% across the industrial names it tracks, while noting that some gearing is “technical” (for example, AIMS Apac’s 26.8% reflects S$621 million of perpetual securities treated as equity rather than debt). On operations, it reports Frasers Logistics portfolio occupancy at 99.8% for logistics/industrial (and 88.4% for commercial), reinforcing the idea that well-leased “sheds” can support distributions when financing conditions are only gradually improving.
By comparison, other property segments show more mixed signals, which helps industrial and logistics stand out in relative terms. The Kopi Notes says Singapore suburban retail occupancy is above 98% at major retail REITs, but Orchard Road assets face softer demand from declining tourist discretionary spend, with average retail REIT yield listed at 5.0–5.8%. In offices, it cites JLL data that CBD Grade A rents have stabilised around S$11–12 per sq ft per month as at Q1 2026, while vacancy has ticked up to about 8%. Against that backdrop, the “Singapore logistics industrial property REIT 2026” theme looks less like a fad and more like a convergence: easing rate pressure, tight domestic leasing, and occupancy and reversion evidence that is clearest in Singapore-focused portfolios.
Why are industrial and logistics REITs seen as a bright spot in 2026?
What do the latest Singapore industrial indices show for 1Q 2026?
Which industrial REITs show the strongest rental reversions in the scorecard?
How do yields and occupancy look for industrial, logistics, and data centre exposure in 2026?
What should investors watch in a Singapore logistics and industrial property REIT approach for 2026?