The 2026 sourcing conversation around Vietnam changed fast because trade policy changed fast. The United States Trade Representative took final action on July 23, 2026, imposing a permanent 12.5% Section 301 duty on goods from Vietnam, effective at 12:01 a.m. eastern on July 24, 2026. The same minute, the temporary Section 122 surcharge expired, so importers saw no gap between the temporary and permanent measures. This 12.5% sits on top of standard MFN apparel duties that range from 0 to 32% by product type, which means buyers must model category-by-category landed cost instead of assuming a single headline rate.
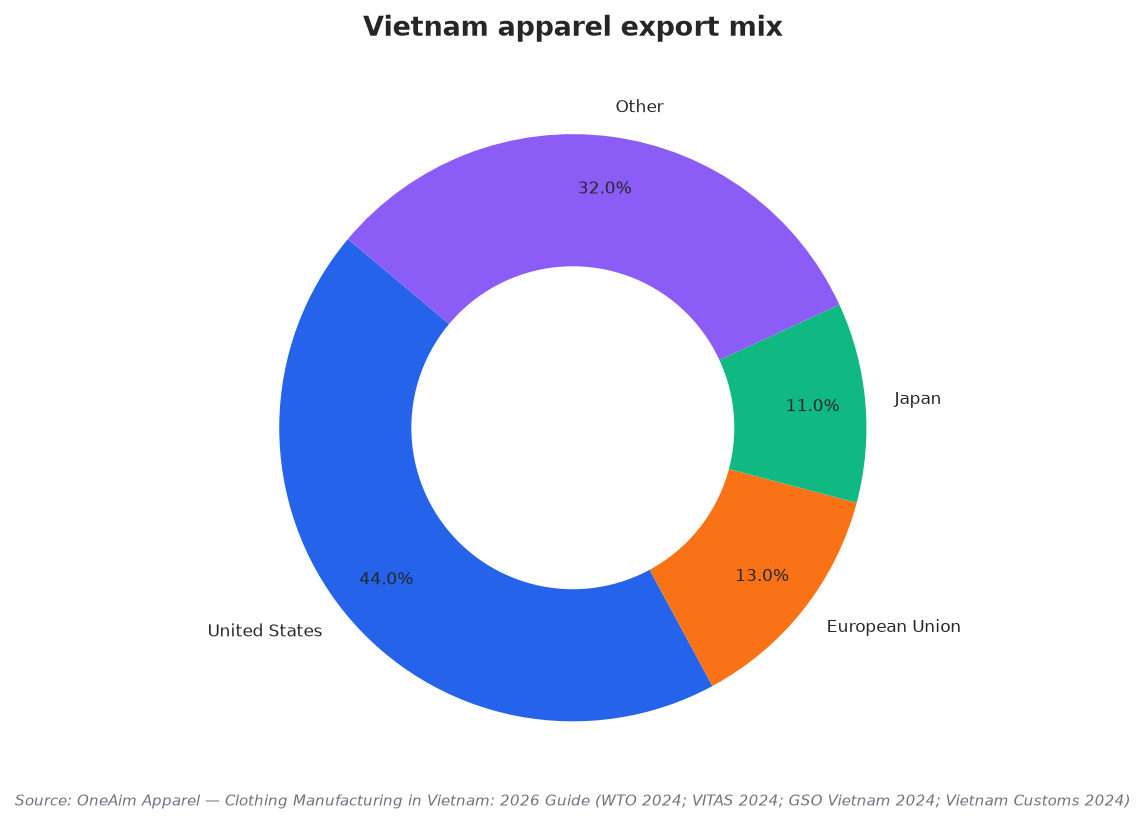
At the same time, Vietnam still looks structurally important in the global map. Vietnam holds 6.1% of global apparel exports, and it shipped $44B in 2024 (WTO, 2024). Vietnam also became the largest apparel supplier to the U.S. market during several periods in 2025, overtaking China, according to industry data summarized by Capital World Group. Another compilation of manufacturing statistics cites Vietnam exports at $46B, reflecting how different sources can report different totals and why brands increasingly validate numbers by scope and definition before committing capacity. In the domestic market, one forecast puts Vietnam’s clothing market at nearly USD 5.26 Billion in 2025, projected to grow at a CAGR of 12.80% between 2026 and 2035.
What Changes in 2026: U.S. Costs Rise While Other Markets Stay Steady
For the Vietnam textile apparel sourcing shift 2026, the biggest pivot is how brands separate “U.S. sourcing” from “non-U.S. sourcing.” One tariff guide says the United States now applies the 12.5% Section 301 duty with no expiration date and no statutory rate cap, and that it remains until USTR affirmatively changes it. The same guide notes that outside the United States, “nothing has changed,” pointing to continued preferential access through EVFTA, UKVFTA, CPTPP, VKFTA, and VSFTA, plus the UAE CEPA and VIFTA with Israel. Separately, a Vietnam manufacturing guide states that EVFTA phases most apparel tariffs to 0% by January 2026, but only for products that meet yarn-forward rules of origin.
Brands are also watching how Vietnam’s relative advantage shifts versus China under U.S. policy. One comparison article states that on April 9, 2026, a U.S. “reciprocal tariff” on Vietnamese goods took effect, and for textile and garment products this meant a sudden leap to nearly 46%. It adds that with existing 15–16% baseline duties, Vietnamese textile and garment exports to the U.S. face combined average duties of 61–62%. The same source says the U.S. and China reached a framework agreement in May 2026 to mutually reduce tariffs on approximately $30 billion worth of goods each, with textiles, apparel, and footwear named as priority categories for relief, and it expects Chinese apparel tariffs that had reached as high as 55% to fall below 20%.
The practical outcome is a more segmented sourcing playbook. For U.S.-bound programs, some teams will split orders or re-price, because the July 2026 permanent duty stacks on top of 0–32% MFN rates, and earlier 2026 reporting highlights how quickly combined duties can climb depending on the measure and baseline. For EU-bound programs, brands may lean harder into Vietnam when they can satisfy EVFTA’s yarn-forward requirements and capture tariffs phased to 0% by January 2026. And across channels, companies are still pursuing China-plus-one and multi-country strategies, with Vietnam repeatedly positioned as a key node because of trade agreements and supplier depth, even as buyers treat tariffs as a long-term factor rather than a short-term disruption.
What permanent U.S. duty applied to Vietnam starting in July 2026?
Do standard U.S. apparel duties still apply on top of the 2026 measure?
What does the article mean by the Vietnam textile apparel sourcing shift in 2026?
What does EVFTA change for Vietnam apparel shipments into the EU by 2026?